Compare 0% APR balance transfer credit cards for 2026. Use our free calculators, compare top offers, and find no-fee cards to eliminate interest.
0% Balance Transfer Credit Cards: Stop Paying Interest
Carrying a credit card balance at 20%+ APR is the most expensive debt most Americans hold. A balance transfer moves that debt to a new card with a 0% introductory APR — typically for 12 to 21 months — so every payment attacks the principal instead of feeding interest. US Balance Transfers helps you do it right: compare today’s best 0% APR balance transfer offers, calculate exactly how much you’ll save with our free tools, and avoid the fee traps that eat into your savings.
Free Balance Transfer Calculators
Not sure a transfer is worth it? Run the numbers before you apply.
- Balance Transfer Savings Calculator — see how much interest you’d save by moving your balance to a 0% APR card
- Balance Transfer Fee Calculator — find out what that 3% or 5% fee really costs you.
- Credit Card Payoff Calculator — compare paying down your current card vs. transferring.
- Minimum Payment Trap Calculator — see how long minimum payments keep you in debt.
Balance Transfer Guides:
How Balance Transfer Credit cards Work
Step 1: Apply for a card with a 0% intro APR balance transfer offer
Start by comparing 0% APR balance transfer cards and applying for the one that fits your payoff timeline. Look at three numbers: the length of the introductory period (usually 12 to 21 months), the balance transfer fee (typically 3% to 5% of the transferred amount), and the regular APR that kicks in after the intro period ends. Most of the best offers require good to excellent credit (a FICO score of 670 or higher), so check your score before applying — each application triggers a hard inquiry. One more thing to verify: the credit limit you’re likely to get. There’s no point in a great offer if the limit won’t cover the balance you want to move.
Step 2: Transfer your high-interest balance
Once approved, initiate the transfer through your new card’s website, mobile app, or customer service line — you’ll need the account number and the exact payoff amount of the old card. Most issuers require you to request the transfer within 60 to 90 days of opening the account to qualify for the promotional 0% rate, so don’t sit on it.
Two rules to know: you generally cannot transfer a balance between two cards from the same bank (no moving Chase debt to another Chase card), and the transfer fee is added to your new balance — a $5,000 transfer with a 3% fee becomes $5,150 on day one. Transfers take 5 to 7 business days to post, so keep making minimum payments on the old card until you confirm the balance moved.
Step 3: Pay it down interest-free before the intro period ends
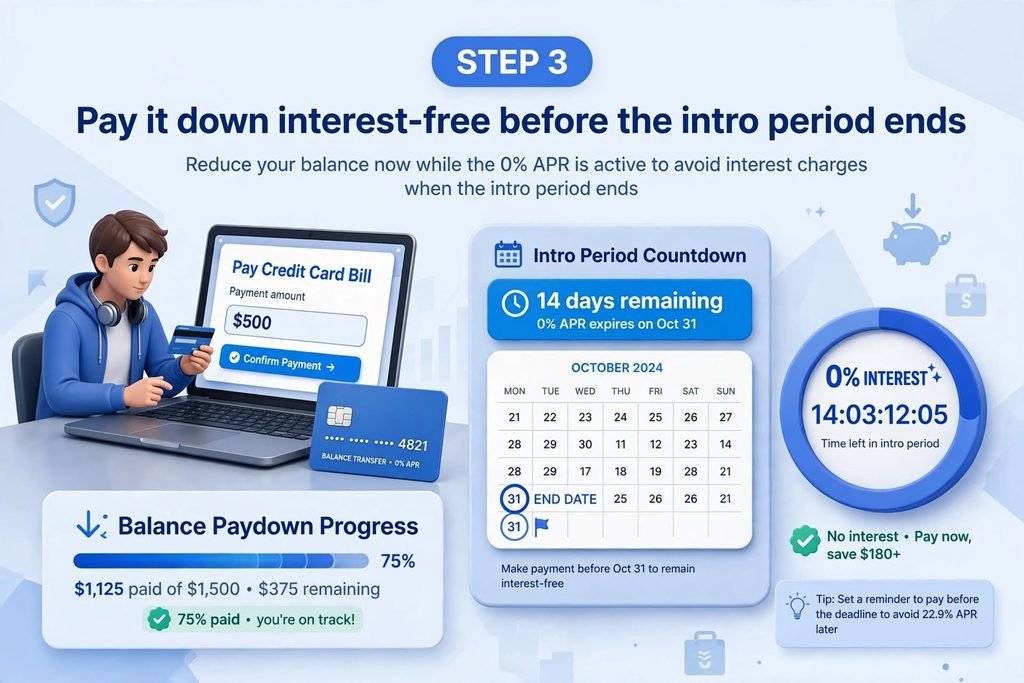
This is where the savings happen — but only if you finish the job. Divide your total transferred balance (including the fee) by the number of months in your intro period; that’s your monthly target. On a $5,150 balance with an 18-month 0% window, that’s about $287 a month. Set up autopay for at least that amount — one late payment can void the promotional rate on some cards.
Avoid new purchases on the transfer card: purchases often accrue interest immediately at the regular APR, and payments may be applied to the transferred balance first. If any balance remains when the intro period expires, it starts accruing interest at 20%+ APR, which can wipe out your savings. Mark the end date on your calendar now.
Frequently Asked Questions about balance transfer credit card
1. What is a balance transfer credit card?
A credit card that lets you move existing high-interest debt onto a new card with a 0% introductory APR, usually lasting 12 to 21 months. During the intro period, 100% of your payment goes toward principal instead of interest. You pay a one-time fee of 3% to 5%, but the interest savings almost always outweigh it if you pay the balance off in time.
2. How much does a balance transfer cost?
The main cost is the transfer fee: 3% to 5%, with a $5 to $10 minimum. Transferring $8,000 at 3% costs $240 — versus roughly $160 per month in interest at 24% APR if you leave it. A handful of cards charge no fee at all, though usually with shorter 0% periods.
3. Is a balance transfer worth it?
Usually yes, if you can pay off the balance before the 0% period ends and the fee is less than the interest you’d otherwise pay. It’s not worth it if you’ll only make minimum payments and still owe most of it when the regular APR kicks in. Run your numbers through a balance transfer savings calculator first.
4. Do balance transfers hurt your credit score?
Expect a small temporary dip from the hard inquiry and new account. But transfers often improve scores over the following months — consolidating balances can lower your credit utilization ratio, which is about 30% of your FICO score. Net effect is usually positive within 3 to 6 months if you pay steadily and don’t add new debt.
5. Can I transfer a balance with no fee?
Yes — a few cards charge no transfer fee. The trade-off is usually a shorter 0% period (6 to 12 months vs. up to 21). If your balance is small enough to clear in the shorter window, a no-fee card can be cheapest overall.
6. How long do 0% balance transfer offers last?
Typically 12 to 21 months from account opening. Longest windows usually come with a fee; no-fee cards tend to cap around 12 months. The clock starts immediately, so have your payoff plan ready before applying.
7. Can I transfer a balance between two cards from the same bank?
No — issuers don’t allow transfers between their own cards. The debt must come from a different bank’s card, which is partly why comparing issuers matters.
8. What happens if I don’t pay it off before the intro period ends?
The remaining balance starts accruing interest at the regular APR (typically 20–29%). Major bank cards charge interest only on the remaining balance going forward. Either way, it can erase your savings — which is why fixed monthly payments from day one are critical.